Digital US Dollars: Why Trump Chose Private Stablecoins
- In Current Affairs
- 06:29 PM, Oct 13, 2026
- Viren S Doshi
Overview
In the race to shape the future of money, two competing visions have emerged: privately issued stablecoins and government-backed Central Bank Digital Currencies (CBDCs).
Under President Donald Trump, the United States has decisively rejected a domestic CBDC and instead championed regulated, US dollar-backed stablecoins through early executive action and the landmark Guiding and Establishing National Innovation for U.S. Stablecoins Act (GENIUS Act) signed in July 2025. The GENIUS Act received strong bipartisan support in both the U.S. House of Representatives and the U.S. Senate. The House of Representatives passed on July 17, 2025, by a 307–122 (or 308–122) margin, with over 100 Centrist Democrats joining Nationalist Republicans to support the bill. Senate passed on June 17, 2025, by a 68–30 vote, with support from a majority of Nationalist Republicans and a significant number of Centrist Democrats.
This choice is reshaping global finance, raising questions about illicit money flows, personal profit motives, and national strategies — while carrying profound implications for the United States, the wider world, Communist China, Democratic India, and other economies. It also raises the question of how far India’s own digital currency plans can align with the American approach.
Let us have a look at all these questions that are going to be increasing in relevance in the days and months ahead.
How Stablecoins Differ from CBDCs
A stablecoin is a privately issued digital token designed to maintain a stable value, typically pegged 1:1 to a fiat currency such as the US dollar.
Issuers (companies like Tether or Circle, or newer entrants) hold reserves — usually cash, short-term US Treasury securities, or similar high-quality liquid assets — and promise redemption at par. Most of these run on public blockchains, enabling fast global transfers.
A Central Bank Digital Currency (CBDC) is a digital form of a country’s official currency issued directly by its central bank. It is a liability of the state itself, just like physical cash or central bank reserves. CBDCs typically operate on permissioned ledgers controlled by the central bank or approved intermediaries.
Key Differences:
Issuer and trust: Stablecoins rely on private companies and the quality of their reserves. CBDCs carry the full faith and credit of the government.
Legal status: CBDCs are (or can be made) legal tender. Stablecoins are contractual claims, not legal tender.
Infrastructure: Stablecoins often use public, open blockchains. CBDCs usually use closed, government-controlled systems.
Access and privacy: Stablecoins can be held in self-custodied wallets worldwide (with varying levels of know-your-customer checks). CBDCs are typically intermediated through banks or apps and designed with greater visibility for authorities.
Purpose: Stablecoins excel at cross-border payments, trading, and crypto ecosystems. CBDCs focus on domestic payments modernization, policy tools (such as programmable welfare payments), and monetary sovereignty.
Pros and Cons
Stablecoins — Pros:
Speed and low cost for cross-border transfers (often minutes and fractions of a cent versus days and high fees in traditional systems).
24/7 availability and global reach on open networks.
Innovation and competition driven by the private sector.
Demand for US Treasuries as reserve assets, supporting the US dollar’s reserve status.
Programmability through smart contracts for advanced financial applications.
Stablecoins — Cons:
Counterparty and reserve risk (even with regulation, an issuer could face problems).
Potential for runs or de-pegging if confidence falters.
Privacy and control trade-offs: issuers can freeze addresses, and public ledgers are transparent to analysis.
Heightened challenges for capital controls and monetary policy in other countries.
CBDCs — Pros:
Virtually no credit risk — it is sovereign money.
Direct policy tools for central banks (targeted stimulus, efficient government payments).
Stronger potential for financial inclusion under official oversight.
Preserves monetary sovereignty and the “singleness of money.”
CBDCs — Cons:
Privacy and surveillance concerns (governments can design high visibility into transactions).
Risk of disintermediating commercial banks if widely adopted as a retail product.
Slower innovation due to bureaucratic design and political constraints.
Limited cross-border utility without complex international agreements.
Potential for government overreach (spending controls, expiration of funds, etc.).
Why Trump Administration Opted for Stablecoins
Trump’s administration has framed the choice in clear ideological and strategic terms. An early 2025 executive order promoted US leadership in digital assets while directing agencies away from a US CBDC. Officials and supporters argue that a government digital dollar would expand federal surveillance power and crowd out private innovation. These concerns have been voiced by libertarian-leaning and pro-crypto constituencies since long.
Finally, in a balancing and yet daring move, the GENIUS Act is in creating a rigorous federal framework for stablecoins: 100% high-quality reserves, monthly disclosures, licensing pathways, consumer protections, and anti-money-laundering rules.
The stated goals are to make America the global leader in digital finance, protect consumers, and cement the US dollar’s dominance by embedding private digital dollars into worldwide payments and settlements.
Backing requirements create structural demand for US government debt.
In short, the policy outsources digital dollar issuance to the private sector under rules that favour American institutions and the greenback the USD, rather than expanding the Federal Reserve’s direct role in retail money.
American Companies Issuing Stablecoins: Numbers, Market Share, and Legal Status
As of October 2026, the global stablecoin market stands at roughly $300–313 billion in market capitalisation, with US dollar-pegged tokens accounting for approximately 99.6% of the total. Around 59 issuers are tracked globally across dozens of products, but the market is highly concentrated.
Tether (primarily offshore-issued USDT) holds about 59–61% market share (~$183–184 billion).
Circle, a US-based public company, holds roughly 24% via USDC (~$73–74.5 billion).
Together, the top two command about 84–86% of the market.
Other notable players include Paxos (US-regulated, issuing PYUSD for PayPal, USDG, and USDP, with combined figures in the low-to-mid single-digit billions), World Liberty Financial (USD1, around $4–4.3 billion or ~1.5%), Ripple (RLUSD, ~$2.4 billion), and various others.
US-linked or US-regulated issuers such as Circle, Paxos, Gemini (GUSD), Anchorage Digital (involved in US-compliant versions), and newer bank or fintech entrants form a significant portion of the regulated segment, though exact counts of fully “permitted” issuers under the still-implementing GENIUS Act remain in flux as final rules take effect by early 2027.
Prior to the GENIUS Act, many issuers operated under state regimes (for example, New York Department of Financial Services trust charters) or as money transmitters, or in less regulated offshore structures. Post-GENIUS, only “permitted payment stablecoin issuers” — subsidiaries of insured depository institutions (banks), federally qualified nonbank issuers (often via Office of the Comptroller of the Currency approval), or state-qualified issuers under substantially similar regimes (with a $10 billion threshold triggering federal oversight) — may issue payment stablecoins for the US market once the law is fully effective. Several large US banks and a consortium of around 21 major banks and asset managers have announced plans for a joint dollar stablecoin targeting launch in the first half of 2027. Individual banks such as SoFi have begun or piloted bank-issued stablecoins. Non-compliant or purely offshore issuers face restrictions on offering to US persons after the transition period.
American companies have expanded circulation through agreements with foreign entities and governments.
These agreements are typically bipartite (US company/affiliate + foreign company or regulator) or tripartite (US company + foreign government/regulator + foreign central bank). They are not usually quadrupartite involving the US government as a formal party. Critically, they do not confer American sovereign backup or guarantees. The GENIUS Act explicitly states that payment stablecoins are not backed by the full faith and credit of the United States, are not guaranteed by the US government, and are not subject to Federal Deposit Insurance Corporation deposit insurance. It is unlawful to market them as such. Reserves consist of private holdings of cash, short-term Treasuries, and similar assets; any “sovereign” connection is indirect through the quality of those US government securities and the regulatory framework itself, not a government guarantee. Circulation abroad relies on the private issuer’s reserves, compliance, and the foreign jurisdiction’s willingness to allow the tokens under its own rules.
Implications for the United States and the World
For the United States:
The strategy strengthens US dollar dominance because the overwhelming majority of existing stablecoins are already USD-backed. Wider adoption in payments, remittances, trade, and crypto trading keeps the dollar as the world’s preferred digital currency. It boosts demand for US Treasuries (as required reserves), helping fund the government and potentially supporting lower borrowing costs. Clear rules attract companies, jobs, and investment in fintech and blockchain. Risks include potential runs on stablecoins if confidence drops, questions about private companies earning seigniorage-like profits from issuing money-like instruments, and the ongoing need for strong oversight of illicit finance.
For the World:
Stablecoins promise faster, cheaper cross-border payments and 24/7 settlement compared with traditional banking.
In countries with high inflation or weak currencies, people may prefer holding digital dollars for stability — helpful for individuals but reducing reliance on local currencies.
This largely reinforces the existing dollar hierarchy rather than creating multipolar alternatives in the near term.
Risks include “digital dollarisation”: easier capital flight, harder capital controls, and potential financial instability in emerging markets during crises.
Overall efficiency gains in global finance come with greater dependence on US policy and infrastructure.
Implications for Communist China
Communist China has long banned private cryptocurrencies and is aggressively developing its own digital yuan (e-CNY), a state-controlled CBDC, plus cross-border experiments such as mBridge with partner countries. US promotion of private USD stablecoins competes directly with Communist China’s vision of state-led digital currency systems. It entrenches US dollar use in global digital payments and trade, countering Chinese Communist efforts to reduce US dollar dependence amid geopolitical tensions and sanctions. Communist China may accelerate its CBDC push, promote yuan-linked systems among BRICS partners, or explore controlled private yuan-pegged instruments. USD-pegged private stablecoins are viewed by Communist China as a threat to monetary sovereignty, capital controls and Communist efforts for de-dollarisation. Geopolitically, this forms part of a broader “currency war” in the digital age: the Democratic US private-market approach versus Communist China’s centralised model and push for de-dollarisation.
Implications for Democratic India
India shows high individual crypto adoption (among the world’s largest markets by some metrics), yet its official stance remains cautious about crypto or digital currencies, though it has clearly stated that it is not interested in de-dollarisation and is okay with USD as global reserve currency. For digitising currency, the Reserve Bank of India is focused on its own Digital Rupee (e₹) CBDC, with ongoing retail and wholesale pilots since 2022. These are expanding into welfare payments (using programmability for targeted subsidies), tokenized bonds and certificates of deposit, and cross-border experiments (with Singapore, the United Arab Emirates, and Bank for International Settlements projects).
The central bank views increasing usage of private crypto and stablecoins cautiously from the point of view of monetary sovereignty, monetary policy impacts, capital controls, financial stability, “singleness of money” and uncontrolled bank exposure to crypto assets. Crypto is not illegal in India (it is taxed - 30% on gains plus tax deducted at source - and it is subject to anti-money-laundering rules), though it is yet to be legalised by licensing.
Implications for Other Countries
Benefits include better access to stable value storage and cheaper remittances or payments. Risks centre on accelerated dollarisation, loss of seigniorage revenue, harder capital controls, and potential instability.
India’s Plans and Potential Alignment with the US Approach
India supports technologies such as blockchain, tokenisation, and distributed ledger technology while remaining cautious of private crypto. India is exploring CBDC interoperability, including proposals within BRICS for linking national digital currencies for trade and tourism payments without creating a common currency. On the same lines, limited direct alignment can exist on private USD stablecoins as follows:
Cross-border payment pilots: India’s Digital Rupee experiments could eventually include regulated interoperability with USD systems - US-regulated stablecoins under strict conditions.
Technology and standards: Shared interest in secure blockchain/tokenization, anti-money-laundering standards, and efficient settlement.
Trade and remittances: Regulated USD stablecoins could lower costs for India-US corridors if India allows controlled access (for example, for exporters and importers under foreign-exchange rules).
Geopolitical balance: As democracies, both countries share interests in open financial innovation versus Communist China’s closed model. India could selectively adopt best practices from the GENIUS Act (reserves, disclosures, licensing) for any future domestic regulated digital assets while keeping the Digital Rupee as the core. India's UPI is an excellent and highly successful example of public-private partnership for easing payment systems. India can seek facilitation for UPI against allowing limited interoperability.
While India advances its CBDC and tokenised markets and the US expands regulated USD stablecoins, limited bridges for efficiency are possible, with India maintaining strong guardrails.
Digital Dollar: Vulnerability to Black Money and Money Laundering — or Greater Resilience?
Public blockchains underlying most stablecoins create an immutable, transparent ledger. Blockchain analytics firms can trace flows far more effectively than traditional cash or opaque correspondent banking in many cases. Issuers of major regulated stablecoins can freeze addresses upon law-enforcement request. Properly regulated systems with strong reserves, audits, and Bank Secrecy Act-style compliance can improve overall financial integrity compared with unregulated crypto or pure cash.
However, risks remain. Once tokens leave regulated exchanges or issuers and move into self-custodied wallets or decentralized protocols, visibility fragments. In such situations, Stablecoins can become a preferred vehicle for certain illicit activities like sanctions evasion, large-scale laundering, and some forms of fraud as they combine dollar stability with speed and borderlessness.
As it rolls out, loopholes exploited by sophisticated actors would come to the fore. Data from analytics firms show stablecoins accounting for a share of illicit crypto volume in recent years, even as overall illicit shares of total volume remain relatively small.
Well-designed regulation, real-time analytics, international cooperation, and issuer freeze capabilities can make the system more resilient than cash or poorly monitored traditional channels. Weak implementation or rapid growth without matching oversight can expand opportunities for black money. The outcome hinges on system preparations, enforcement and continuous adaptation by regulators and industry. A nation like India is best suited to adapt and adopt digital currencies as it has excelled in digital payments and as it strengthens the digital payment ecosystem against fraud on a continuing basis.
“Stablecoins for Trump's Personal Profit”
A persistent narrative claims the pro-stablecoin and pro-crypto push primarily serves Trump’s and his family’s financial interests. Opponents get an opportunity to level charges because of Trump’s involvement in this business. But the claim that the US digital currency policy was formed solely for personal enrichment clearly oversimplifies a broader strategic agenda of the United States as a global reserve currency state having trillions in debt.
Trump family-linked ventures, particularly World Liberty Financial (co-founded with associates including the Witkoff family, with Trump sons involved in operations), have generated revenue from token sales and related activities. Financial disclosures for 2025 showed revenues worth hundreds of millions of dollars linked to these crypto businesses, reflecting corresponding hundreds of millions of dollars of investment. World Liberty has issued or co-owns a dollar-pegged stablecoin known as USD1. Profits from these revenues are soaring as the promoters sell their stakes to other investors. Nevertheless, the share of these companies in the total crypto or stablecoin business is around 1 per cent.
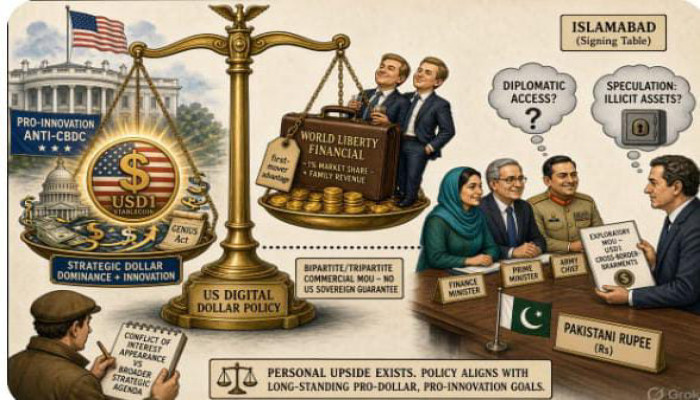
In January 2026, Pakistan’s Virtual Asset Regulatory Authority signed a memorandum of understanding with SC Financial Technologies, a Delaware - registered affiliate of World Liberty Financial, to explore integrating the USD1 stablecoin into regulated digital payment architectures for cross-border payments, including for arms purchases and for remittances. The arrangement involves collaboration with Pakistan’s central bank so the token can operate alongside Pakistan’s own digital currency infrastructure. Pakistani officials, including the finance minister, prime minister, and army chief, attended the signing, which featured Zach Witkoff (World Liberty CEO and son of a Trump Administration envoy).
As of mid-2026, it remained largely exploratory, with limited concrete pilots or large-scale transactions reported, yet it provided Pakistan diplomatic access and visibility for the Trump-linked firm.
Similar exploratory or technical partnerships by other US issuers with foreign payment firms, exchanges, or regulators exist.
Trump Family commercial ties create a situation of conflict of interest. Defenders counter that Trump has long advocated American technological leadership, that the GENIUS Act imposes real consumer and reserve protections, that the dollar-strengthening rationale is coherent, and that family businesses stepping back from day-to-day control after inauguration mitigates concerns. It is also reported that investors in some Trump-associated tokens have experienced losses.
Ethics rules for Presidents differ from those for other officials, and the Administration has rejected conflict claims.
On the other hand, Pakistan is known for its military dominance and probable illicit assets of its top brass. This gives rise to speculation that it wanted this agreement for parking such ill-gotten wealth safely. It is also reported that this move, together with a deal for purchasing drones from a Trump Family-related company by Pakistani Military leadership through crypto payments, has given it access to the White House, of course at the cost of the Pakistani Economy and its drone import trade with Communist China and Jihadi Turkey.
Personal financial upside exists in a kind of first-mover advantage, while the policy clearly aligns with longstanding pro-innovation, anti-CBDC, and pro-dollar positions held by significant parts of the Republican coalition and the crypto industry.
Looking Ahead
Trump’s bold move for regulated private stablecoins seeks to project American financial power into the digital age without expanding the state’s direct monetary footprint.
American companies — from established players like Circle and Paxos to newer entrants and planned bank consortia — are expanding issuance under tightening rules, with market concentration remaining high (top two issuers ~85%).
Cross-border agreements, such as the Pakistan MoU, illustrate how private US firms can seed circulation abroad through bipartite or tripartite arrangements with certain pliant foreign regimes and central banks, without any formal US sovereign guarantees.
Whether the overall system strengthens resilience against black money or creates fresh vulnerabilities will depend less on the technology itself than on the quality of rules, enforcement, and international coordination through platforms like FATF (Financial Action Task Force).
All said, the system offers speed, innovation, and US dollar reinforcement for the United States while creating complex challenges for Communist China, which is clearly bent upon pushing de-dollarisation.
India’s CBDC-focused path and clear stance against de-dollarisation and successful UPI, can coexist with US systems through careful, limited interoperability.
Disclaimer: The opinions expressed within this article are the personal opinions of the author. MyIndMakers is not responsible for the accuracy, completeness, suitability, or validity of any information on this article. All information is provided on an as-is basis. The information, facts or opinions appearing in the article do not reflect the views of MyindMakers and it does not assume any responsibility or liability for the same.
 Loading...please wait
Comments